For all those future vets… how to pay for your uni tuition fees…
HECS/HELP: Is it more of a “hex” than a “help”? What does it even mean?
What is HECS debt?
HECS stands for Higher Education Contribution Scheme. HECS is the type of loan you take out as a student to pay your contribution of your tuition fees.
HELP stands for the Higher Education Loan Program. This is the overall program that provides loans to eligible students (whether at TAFE, college or university).
When you attend university or an approved higher education provider* you can take out a HECS-HELP loan to pay for your studies.
Once you take this loan out then the loan amount is typically referred to as your “HECS debt”.
To become a vet, then your education provider will need payment for your tuition. Studying to become a vet takes between 5-7 years depending on your university/higher education provider and your course structure. That can be 5-7 years of tuition fees.
Sounds a bit scary? Well, any debt is at least a teensy scary in my opinion, however, many students do need to go into some debt to fund their university studies. So I recommend you take a deep breath, be assured you are not alone, accept your debt fate to a certain degree and lets move on to figuring out what a HECs debt actually entails. I promise there is light at the end of the tunnel…keep reading.
What does HECS debt include?
A HECS-HELP loan is used to pay your Student Contribution Amount.
This leads to the obvious…
So what is your Student Contribution amount?
If you are enrolled in an education institution that is a Commonwealth supported place (CSP)*, the Australian Government pays some of your tuition fees while you pay the remaining portion. This remaining portion of tuition fees is called your ‘student contribution amount’.
* You can only get a HECS-HELP loan if you are enrolled in a Commonwealth supported place (CSP).
Each unit of study is classified into a student contribution band, that differs according to the study area of the unit.
For example, the 2024 maximum student contribution amount (per Equivalent Full Time Student Load (EFTSL)) for a Veterinary Science student would be $12,720. Note, while this is a maximum student contribution amount, that maximum is only for 1 year’s ie 2024 tuition.
So, after a few years of study at a uni…how long does it take to become a vet again? …oh that’s right it can be between 5 and 7 years … you can see how the debt can mount up to many thousands depending on how much you need to borrow.
What does HECS debt not include but you still may need to pay for as a uni student?
A HECS-HELP loan does not and I repeat DOES NOT cover the following:
- Accommodation
- Living expenses (food, utilities, transport)
- Laptops or text books
It is purely to cover tuition fees.
HELP loan limits
A loan limit means the maximum HELP will loan to an individual student starting a course at a CSP in 2024.
For 2024, the HELP loan limits are: $121,844 for most students and
- $174,998 for students studying:
- Medicine, dentistry or veterinary science courses leading to initial registration.
Remember this is the cap for a HECS HELP loan will let you borrow from them, not necessarily, all you need to borrow to cover all your expenses. Remember they are only lending funds to you to cover the portion of tuition fees that the Australian government does not cover.
It’s good to know there is a limit to how much you can borrow. To me given the high level maximum amount quoted as examples here, this says that for most courses this won’t limit what most people would want to achieve. For example, if you take as a very rough example, using the 2024 max student contribution amount of $12, 720 , then (assuming this is for a full time student) multiplying this by 5 for a 5 year course rough estimated total = $63,600 (remember the actual annual amount will differ each year so this only a rough example) . This is considerably less than the total max threshold for vet students of $174,998 (quoted above).
However, if I fail too many units and need to re sit exams then those course fees will likely need to be paid again, and possibly again ☹ and this is where a financial borrowing limit comes into place.
Remember, the borrowing limit referred to here, HELP loan limits, means that’s the maximum they would lend you for tuition only.
Census/Administrative dates
“I keep reading about Census dates and Administrative dates relating to HECS-HELP loans.
What is a Census date? What is an Administrative date? What is the difference?”
Census date
A census date is the last day you can make an upfront payment, apply for a HELP loan, accept an offer in a CSP or formally withdraw.
Each university or higher education provider sets their own census date, so the date will be different for different courses and providers.
If you do not submit your HELP loan form by the census date:
- you will not be eligible to access a HELP loan for that study period
- your enrolment and subsidy (if enrolled in a CSP) will be cancelled.
Administrative date
Some higher education providers set an extra deadline date, called an administrative date, which is before the census date. If your provider has an administrative date, you must submit your HELP loan form, accept your offer in a CSP, pay your fees or withdraw your enrolment before this date.
If you miss the administrative date, you may have to pay a late enrolment fee or a late withdrawal fee.
To find out if your provider has an administrative date you should contact and confirm with your higher education provider.
Recent Changes to Indexation of HECS/HELP Loan Debt
“I heard on the news that the indexation rate that applies to HECS debt has been changed. It sounds as though its meant to reduce my debt and to be better for me but I don’t really understand what it means. ….What does it all mean and how will I benefit?”
To better understand how the proposed, indexation legislation changes impact you, then you should have a basic idea of the process used to calculate the loan amount. I’ll go through the process using an example below. This does not cover every single fee/charge associated with HECS/HELP loans but helps explain the indexation process applied to them.
When you take out a HELP loan to pay off your student contribution amount you are taking out a loan for the student contribution amount you need to pay for the units you are studying.
The loan is based on an estimated cost of the student contribution amount.
Example:
Let’s say you have a 5 year university degree course. You need to pay your student contribution amount for each of the units you study in those 5 years. The below example (not real amounts) shows nice round figures for each year’s student contribution amounts. (The nice round figures is how you know this is only an example ?).
For 2020-2022 Student contribution amount for your units by the census date was $10,000 so $30,000.
For 2023 Student contribution amount for your units by the census date was $11,000.
For 2024 Student contribution amount for your units by the census date was $12,000.
Assuming you did not repay any of the loan amount between 2020 and 2024 ie you made no repayments while still studying, then at the end of the 5-year course your total student contribution amount paid across to your higher education provider was $53,000.
Let’s assume you borrowed this amount using the HELP loan facility. This is a loan taken out with the Australian government which the ATO effectively administer. The ATO will assess your loan balance at 1 June each year and index any amount that was unpaid for more than 11 months. This means a index factor (currently the Consumer Price Index (CPI)) would be applied to the portion of your outstanding loan balance that remains unpaid for more than 11 months as at 1 June. This would typically increase that portion of your loan by that rate.
On 1 June 2020 – HECS HELP Loan balance borrowed $10,000
Indexation – No indexation is applied by the ATO as loan amount was unpaid in total for less than 11 months).
June 2020 Total HECS/HELP loan balance of $10,000
On 1 June 2021 – HECS HELP Loan balance borrowed is now $20,000
Indexation – Indexation is then applied to the initial $10,000 from 2020 as this remains unpaid for more than 11 months.
2021 CPI = 0.6%. So $10,000 * 0.6% = $60 inflation adjustment. This increases the >11month balance to $10,060.
Unindexed portion – In addition, there is the student contribution amount for 2021 unpaid for < 11 months of $10,000 (remains unindexed at this date).
Therefore, the June 2021 total combined inflation adjusted loan balance is now $20,060.
1 June 2022 – Loan balance now $30,060. ($20,060 from end of 2021 plus $10,000 2022 Student contribution amount borrowed ).
Indexation – Indexation is applied to the portion of the loan that is unpaid for > 11months. This is the $20,060.
2022 CPI = 3.9% So 20,060 * 3.9% = $782.34. This increases the unpaid for >11month balance to $20,842.34.
Unindexed portion – In addition, there is the student contribution amount for 2022 unpaid for < 11 months of $10,000 (remains unindexed at this date).
June 2022 Total inflation adjusted loan balance = $30,842.34
1 June 2023. Loan balance has increased now to $41,842.34 (pre indexation). ($30,842.34 from end of 2022 plus $11,000 2023 Student contribution amount borrowed).
Indexation – At this point CPI had risen to 7.1%. An adjustment for indexation was 30,842.34 * 7.1% = $2,189.80. This adjustment is purely indexation.
Unindexed portion – In addition, there is the student contribution amount for 2023 unpaid for < 11 months of $11,000 (remains unindexed at this date).
June 2023 Total inflation adjusted loan balance is now $44,032.15
1 June 2024. CPI has reduced to 4.7%.
HECS loan plus 2024 student contribution amount borrowed = $44,032.15 +$12,000 ie $56,032.15.
Inflation adjustment= 44,032.15*4.7% = $2,069.51
Unindexed portion – In addition, there is the student contribution amount for 2024 unpaid for < 11 months of $12,000 (remains unindexed at this date).
June 2024 Total inflation adjusted loan balance is now $58,101.66.
For a tabular view of the above calculations refer below:
Impact of indexation
This means, $5,101.66 of the loan balance was purely inflation adjustments added to the initial $53,000 course Student Contribution Amount borrowed (across the 5 year period). Obviously, the bigger the rate then the bigger the inflation adjustment will impact your debt balance.
The reason the rates jumped dramatically was due to a variety of macro-economic factors but primarily by the interest rate increases imposed by the Reserve Bank Australia to reduce inflation. Regardless of the cause, where we had for a few years a stable low CPI rate, meaning debt balances were not impacted dramatically by changes, this has now changed and changes are potentially and in 2023, were certainly, more volatile.
Recognising this is a potentially significant impact for students, the government have proposed new legislation to allow that HECS debt should be indexed by the lower of the CPI or the Wage Price Index (WPI). The idea behind this is to provide a more stable indexation rate.
In 2023 the WPI was 3.2% compared to the CPI of 7.1%. This would have meant, using the example above, a reduction of the inflation adjustment to $986.95 compared to $2189.90 ie a difference of $1202.85.
For 2024 the WPI is 4.0% instead of 4.7% so the differences are not always as pointed. However, when it comes to loan adjustments and percentages applied then it all adds up.
Note for those worrying about the poor borrowers who did suffer from the inflation adjustment of 7.1% in 2023, the proposed legislation will allow adjustments to be backdated to 1 June 2023 so assuming the legislation gets passed, these people will get a credit back. Yay!! Here is finally a reason to check on what laws have gone through in parliament!! This may directly impact you!
How do I avoid inflation adjustments?
The only real answer is for those who have taken out a HECS-HELP loan and who then pay the debt back in total before the debt becomes greater than 11months old. We must note this is extremely impractical for most people. However, it is the only way to avoid additional inflation adjustments to HECS/HELP debt, that are in theory, unnecessary.
So, I’ve got a large HECs debt. Now I’m starting work. I don’t earn a lot yet, but I’ve got this large debt balance. … how much and when do I need to pay it back?
This is where the ATO come in. Its actually always been there – remember those inflation adjustments – that’s done by the ATO.
However, now you are earning income. The unfortunate thing about most income types is Yay MONEY ? but also Yuck TAX ☹. Revenue is tax assessable. You now need to submit tax returns where you may actually need to pay some tax (because you’ve earned some income remember) not just get a nice tax refund.
Your loan balance is sitting with the ATO.
You start earning from a job.
When you earn above a certain amount for the tax year then this is assessed, and a compulsory repayment amount is required from you via your tax assessment, if your taxable reportable income is above the minimum repayment income threshold.
Remember your loan is still sitting there getting inflated each year, if you do not pay any back.
When you prepare your annual tax return, the ATO will assess whether you have earned over the minimum repayment income threshold (repayment income = taxable income plus any net investment losses (remember losses are negative) ) . If you have, they will then apply a repayment rate ( % of your repayment income) and assess this as the minimum compulsory repayment required from you for the tax year.
The minimum repayment rate (%) are subject to change each year and the % will increase the more you earn. The ranges for 2024/2025 coming tax year are in the below extract from the ATO. See link.
https://www.ato.gov.au/tax-rates-and-codes/study-and-training-support-loans-rates-and-repayment-thresholds
Don’t worry you have to have a reportable Income of at least $54,435 to be required to pay anything.
Example of minimum compulsory repayment
So in our previous example, our total HECS/HELP loan inflation adjusted balance was $58,101.66.
If in 2024/2025 you take a first job and have a reportable taxable income of over $60,000 then you will be required to pay 1% of $60,000 ie $600 as a compulsory repayment that first tax year out of the $58,101.66 owed. That’s not actually a lot right? I mean $600.00 being deducted in one go could be quite a hit but across the year it is a small proportion of what you earn. Assuming you are paid monthly this would be $50 a month for that tax year.
To avoid a significant impact at 30 June, generally, your employer will hold back a % proportion from your salary using an estimated Reportable Income level based on the salary they pay you. Any excess or overpayment throughout the year will be sorted out at the point you submit your tax return.
Be aware that as your reportable income increases then the % you are required to repay of your loan balance also increases. So, in the above example if your reportable income becomes $70,000 then you would be required to pay $70,000 x 2.5%=$1,750 the year. That’s a bit more significant. However, remember that is $145.83 per month if that makes it a little more palatable.
What are key points to take away here?
The amount of minimum compulsory repayment will be assessed as part of your annual tax return process.
To avoid a larger, significant impact around tax return time, it is generally advisable to save (or ensure your employer is deducting tax on your behalf) throughout the year to repay these amounts against your loan.
Inform your employer when starting a role, that you have HECS/HELP debt so they can apply a repayment % deduction from your salary for you. Remember this will have the advantage of also reducing your unpaid loan amount throughout the year and thereby reducing the indexation impact just by repaying amounts earlier.
Are there advantages to not paying off my HECS HELP loan as soon as possible?
Well sure, if you don’t repay the loan then of course you have more cash in hand or much more likely more funds in your bank account where your salary gets deposited. You could theoretically start comparing earnings on interest rates versus the indexation rate applied on the unpaid amounts.
Sometimes life happens, we all need to live and we can have both expected and unexpected expenses. We may need to buy a car or help out a friend, pay a hospital bill. This could be on top of more standard bills eg rent, utility bills, car loan, food etc. You may have expenses that simply eat up your salary and paying off only the minimum amount for the HECS HELP loan keeps your head above water.
When just leaving university/college and starting your career as a vet, your focus may be primarily on finding work, paying your rent and bills, and most likely paying off any other loans you may have taken out for which interest is charged eg car loan. Thoughts of a mortgage are probably far away in the distant future. As such, not making extra non-compulsory payments is attractive in the short term.
2 issues with this to bear in mind.
- Your HECS-HELP loan balance will keep getting indexed each year for amounts unpaid > 11months. Depending on your income, the loan balance may not even decrease by the minimum compulsory repayment. This means the balance may keep increasing year by year until the relevant repayment rate becomes greater than the CPI/WPI.
- This HECS HELP loan debt will impact your credit profile.
This is a profile based on existing debt you hold that financial institutions will use to assess whether you are eligible to borrow money from them. Really, they are assessing your expected ability to repay any money they lend you. They will then determine whether you get the go ahead to borrow money from them and the amount they would be willing to lend you.
You may well not be thinking of buying a house or a property any time soon but at some point in your life, you may at least consider it. The vast majority of people need to borrow from a financial institution to fund buying a property. Having a significant HECS-HELP loan could limit what institutions are willing to lend you.
Given the numerous RBA interest rate rises mortgage rates have risen significantly compared to the much more consistently stable and lower interest rates of the mid 2000s to 2021 period. Having a nice clean credit profile makes this a lot easier and this may well be something you consider much more critical at a later date.
Also, bear in mind that how you view this issue upon just starting your career may well differ ten years from now. Having an “I’ll only pay off the minimum I need to” attitude for long periods may negatively impact you (credit wise) down the track ie it may come back to bite you later.
How do I make additional repayments if I need to?
Voluntary repayments can be made to your HECS HELP loan any time by logging into your ATO online account. Voluntary repayments reduce the debt straight away. For it to count within your current year tax assessment then payments should be made a few days before 1 June to ensure they have cleared in time for the indexation process ie to minimise the indexed portion.
Conclusion
This article is intended only to shed some light on HECS/HELP loans, how they are operated and also discuss the impact of the proposed government legislation and how this should benefit students with HECS/HELP debt.
Everyone has different financial circumstances. Please read the article and consider whether any of the items discussed would apply to you.
Is it more of a hex or a help? That depends on your other expenses, your spending habits, and ability to earn. I think of it more as a tool. If you use (manage) it correctly, it can help. If you don’t understand it and don’t keep it under control it could well be a hex for life.
Debt is scary but HECS-HELP debt is one of the methods available to you to get you on the pathway to your chosen veterinary career. We hope this helps you understand it a little further and manage it accordingly. ?
Author:
Scarlett Aston
Kookaburra Veterinary Employment
This information includes the views and opinions of Kookaburra Veterinary Employment and is of a general nature only. Factual information is believed to be correct at the time of writing, however, should not be relied upon and any person should confirm details with the relevant authorities and through their own research prior to acting on any of the suggestions in this article.


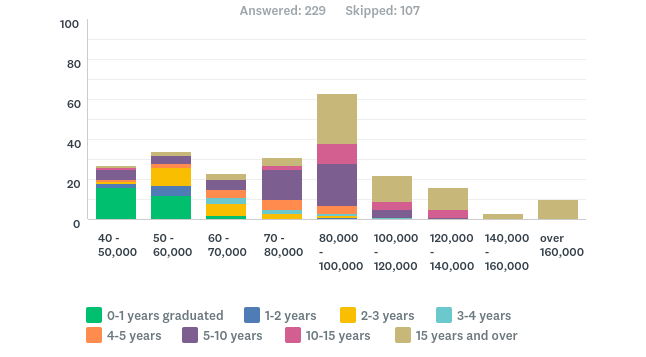
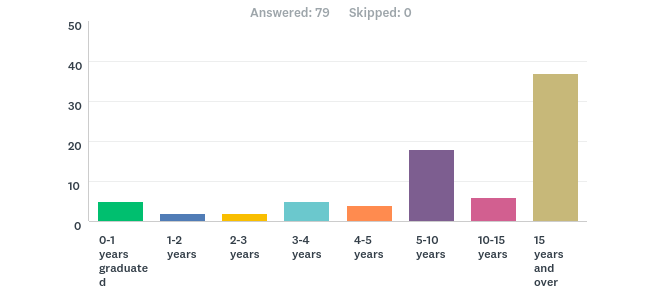
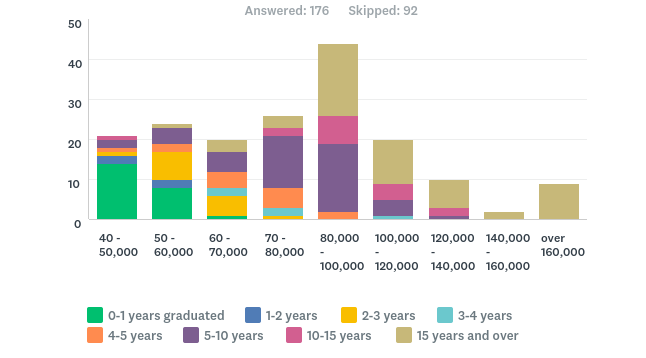
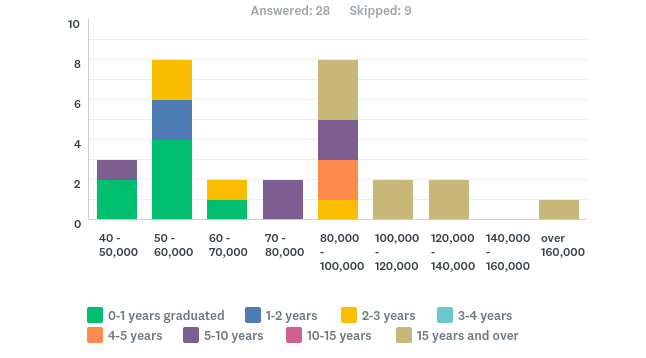
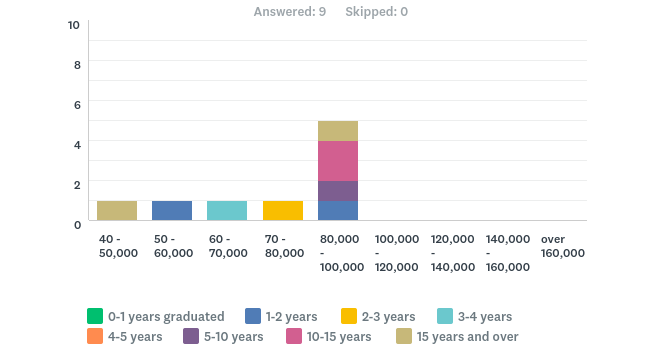
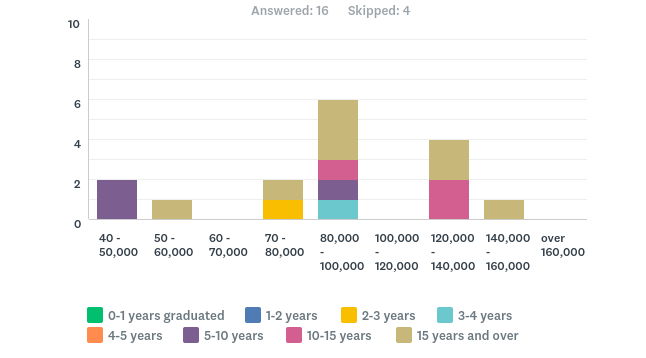
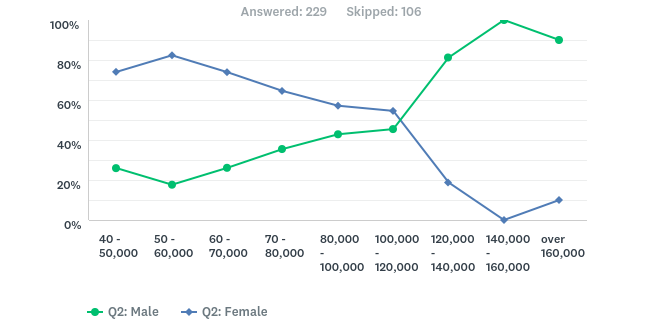
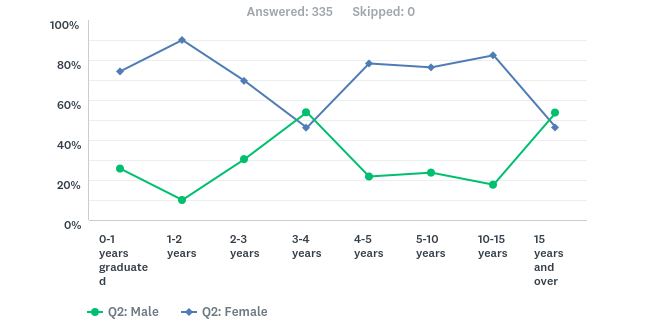
 Some of the most common questions that we get asked at Kookaburra Vets relate to Salary levels. Thanks to all the vets who participated in our survey – the more vets who reply, the more useful this information is. We hope that in future years more of you will take the small amount of time required to complete our survey. We asked for full time annual salary range not including Super.